Writing Off a Tesla for Business in 2026: Section 179, Bonus Depreciation and Canada’s $61,000 Class 54 Rule
Writing Off a Tesla for Business in 2026: Section 179, Bonus Depreciation and Canada’s $61,000 Class 54 Rule

Every fall, accountants across the United States and Canada field the same question from small-business owners: “If I buy a Tesla through the company before year-end, how much can I write off?” In 2026 the answer is more generous than it has been in years, but it hinges on details most buyers never check: the weight rating on the door jamb, the date the vehicle was acquired and, in Canada, whether you took the federal rebate at delivery. This guide walks through both countries’ rules for the 2026 tax year, with worked examples for the Cybertruck, a used Model X and the Model Y, so you can have an informed conversation with your CPA instead of a hopeful one.
Disclosure: some links are affiliate/referral links. If you order or buy through them we may earn a small commission or credit at no extra cost to you. This article is general information, not tax advice; confirm anything you plan to act on with a licensed tax professional. See our disclosure page.
📋 Contents
- The 2026 landscape in one paragraph
- United States: the weight rating decides everything
- How Section 179 and bonus depreciation stack on a Cybertruck
- The used Model X play, and its one trap
- Business-use rules that catch people
- Canada: Class 54 gives you a $61,000 first-year write-off
- EVAP rebate or Class 54 write-off: Canadian businesses must choose
- Timing: why “placed in service” beats “ordered” in both countries
- Frequently Asked Questions
- Key Takeaways
The 2026 landscape in one paragraph
In the US, the federal EV purchase credits are gone: the $7,500 consumer credit and the Section 45W commercial clean vehicle credit both ended for vehicles acquired after September 30, 2025, and no bill to revive them has moved. What replaced them for business buyers is depreciation. The One Big Beautiful Bill Act made 100% bonus depreciation permanent for property acquired after January 19, 2025, and the Section 179 limits were indexed upward for 2026. In Canada the story runs the other way. The federal Electric Vehicle Affordability Program (EVAP) launched in February 2026 with a $5,000 point-of-sale incentive that businesses can also claim, and the Class 54 zero-emission vehicle write-off, which lets a business deduct 100% of up to $61,000 in the first year, was reinstated for vehicles acquired from 2025 through 2029. The catch is that Canadian businesses generally have to choose one or the other.
United States: the weight rating decides everything
US tax law sorts business vehicles by Gross Vehicle Weight Rating, the manufacturer’s maximum loaded weight printed on the certification label inside the driver’s door. The line is 6,000 lb. Above it, a vehicle escapes the “luxury auto” depreciation caps of Section 280F; below it, those caps limit how fast you can write it off, no matter how the vehicle is used. Here is where the current Tesla lineup falls.
| Tesla model | Typical GVWR | US tax class | Maximum first-year write-off (2026, 100% business use) |
|---|---|---|---|
| Cybertruck (AWD, Premium AWD, Cyberbeast) | About 8,200 to 9,200 lb | Heavy vehicle, over 6,000 lb | Full purchase price in year one via Section 179 (up to $32,000 if treated as an SUV) plus 100% bonus depreciation on the rest |
| Model X (used only; production ended March 2026) | Roughly 6,000 to 6,800 lb depending on year, seats and wheels | Heavy SUV, over 6,000 lb on most builds | Section 179 up to $32,000 plus 100% bonus depreciation on the remaining cost, if the door label shows more than 6,000 lb |
| Model Y (all trims, including Model Y L) | About 5,300 to 5,700 lb | Passenger automobile, under 6,000 lb | $20,300 in year one with bonus depreciation, then $19,800, $11,900 and $7,160 a year |
| Model 3 (all trims) | About 4,900 to 5,300 lb | Passenger automobile, under 6,000 lb | Same $20,300 first-year cap as the Model Y |
Two points about that table. First, the passenger-automobile caps are reduced by your business-use percentage, so at 80% business use the first-year ceiling on a Model Y is $16,240, not $20,300. Second, the caps bite less on a Tesla than on a German luxury sedan: a Model Y Premium AWD at about $51,400 delivered is fully depreciated by the end of year three, because $20,300 plus $19,800 plus $11,900 already exceeds the price. The Section 280F figures come from Revenue Procedure 2026-15 and the Section 179 amounts from Revenue Procedure 2025-32; the IRS summarizes both in Publication 946, How to Depreciate Property.
How Section 179 and bonus depreciation stack on a Cybertruck
Section 179 lets a business elect to expense the cost of qualifying equipment in the year it is placed in service, up to $2,560,000 for tax years beginning in 2026, with a phase-out starting at $4,090,000 of total purchases. For vehicles between 6,001 and 14,000 lb GVWR that are classified as sport utility vehicles, Congress added a separate cap, $32,000 for 2026, to close the old “Hummer loophole.” Pickups escape that SUV cap if they have a cargo area at least six feet long that is not readily accessible from the passenger compartment. The Cybertruck’s bed measures about 72.9 inches with the tailgate up, so tax professionals disagree about whether it clears the six-foot test on the interior measurement. In 2026 the argument is mostly academic, and here is why.
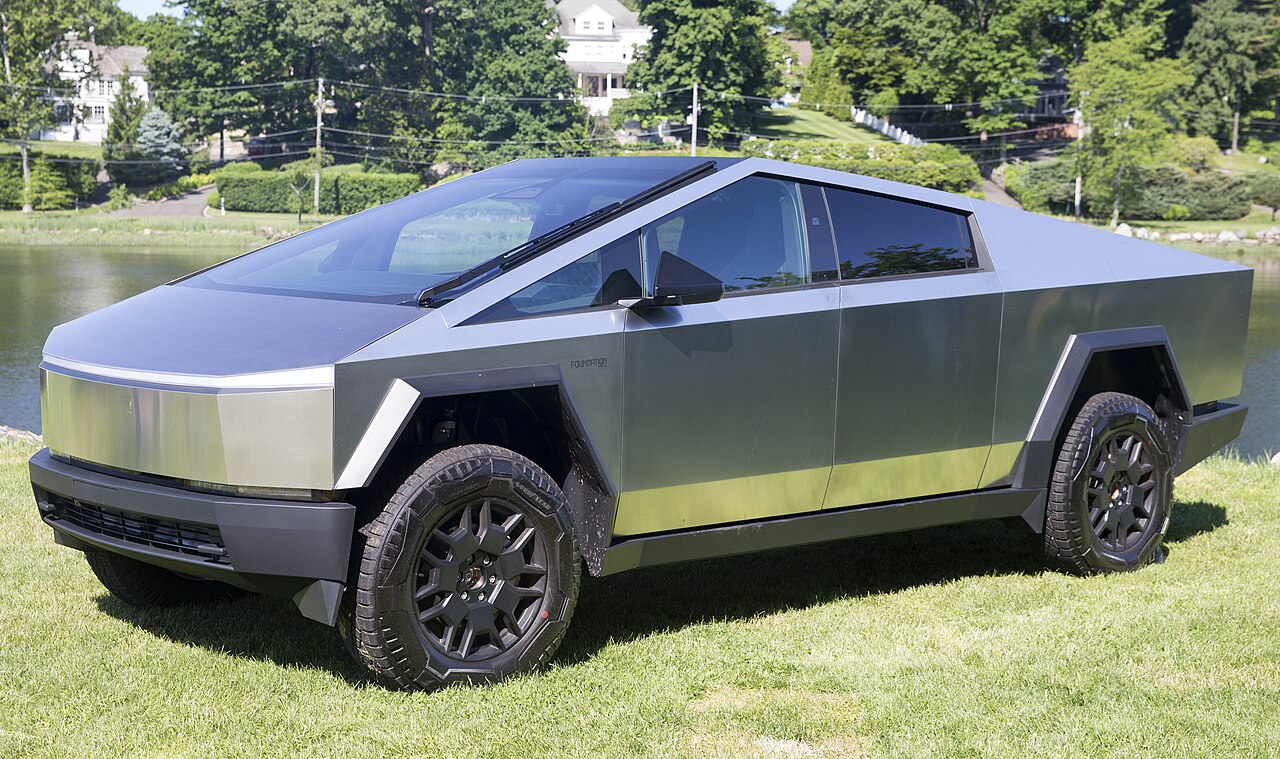
Bonus depreciation under Section 168(k) has no dollar cap for heavy vehicles. Whatever Section 179 does not cover, 100% bonus depreciation can, in the same year. Take a Cybertruck AWD at $69,990 plus roughly $1,995 in destination and documentation fees, call it $72,000, used 100% for a construction or landscaping business and placed in service before December 31, 2026. Treat it as an SUV and you expense $32,000 under Section 179 and $40,000 under bonus depreciation; treat it as a qualifying pickup and you expense the full $72,000 under Section 179. Either way, the entire cost is deducted in 2026. At a combined 35% federal and state marginal rate, that is roughly $25,000 of tax deferred into later years. The same math applies to the $79,990 Premium AWD and the $99,990 Cyberbeast, and a used Cybertruck bought from an unrelated seller qualifies exactly the same way, since both provisions cover used property as long as it is new to you.
The two provisions differ in edge cases. Section 179 cannot create a business loss and is elected vehicle by vehicle; bonus depreciation can produce a loss and applies to a whole asset class unless you elect out. If you are cross-shopping trims, our Cybertruck buying guide covers what changed in the 2026 lineup, and ordering through a Tesla referral link adds three months of Full Self-Driving (Supervised) on top of the 30-day trial, a benefit that is not taxable to you and does not change your depreciable basis.
The used Model X play, and its one trap
Tesla stopped building the Model S and Model X in March 2026, and by mid-summer the new inventory was gone. That has not ended the Model X’s popularity with business buyers, because used property qualifies for both Section 179 and bonus depreciation. A three-year-old Model X in the $50,000 to $65,000 range, bought from a dealer, an auction or a private seller who is not a relative, can be written off in full in 2026 under the same heavy-SUV stacking described above, provided the business-use test is met.
The trap is the door label. Model X GVWR varies with model year, seating layout and wheels: seven-seat cars have been documented above 6,700 lb, while at least one five-seat refresh build carried a label of about 6,020 lb, barely over the line. Never rely on a listing or a forum post. Read the GVWR on the driver’s door certification label, photograph it and keep it in your tax file. Our used Tesla buying guide covers the battery, warranty and inspection side of buying a pre-owned Model X.
Business-use rules that catch people
Vehicles are “listed property” in the US tax code, which means the rules are stricter than for a laptop or a forklift. The ones that trip up Tesla buyers most often:
- More than 50% business use is required in the year the vehicle is placed in service. Commuting from home to a regular workplace is personal use.
- If business use later drops to 50% or below, the accelerated deductions are recaptured as ordinary income.
- A contemporaneous mileage log is the only evidence that reliably survives an audit. The Tesla app’s trip data or a mileage app works; a reconstruction in March does not.
- Claiming depreciation locks that vehicle into the actual-expense method. You cannot switch to the standard mileage rate later, even though it is attractive in 2026 at 72.5 cents per mile through June and 76 cents from July 1, per the IRS standard mileage rate schedule.
- State conformity varies. California does not follow federal bonus depreciation and caps its own Section 179 deduction at $25,000, so a Cybertruck expensed in full federally still depreciates slowly on the California return.
If the truck or SUV doubles as a mobile office between job sites, a JOWUA foldable car tray (from about $15, use code TSLNA for 5% off) turns the passenger seat into a laptop desk and, like the vehicle itself, is a deductible business expense when used for work.
Canada: Class 54 gives you a $61,000 first-year write-off
Canada does not use a weight test for passenger vehicles. Instead, the Income Tax Act caps how much of a passenger vehicle’s cost a business can depreciate. For 2026 the ordinary Class 10.1 cap rose to $39,000 before tax, but a zero-emission vehicle goes into Class 54, where the cap is $61,000 plus the non-recoverable federal and provincial sales tax. The Department of Finance’s 2026 automobile limits announcement confirmed the $61,000 figure is unchanged for both new and used vehicles acquired in 2026.
The more important number is the first-year rate. Class 54 normally depreciates at 30% on a declining balance, but the enhanced first-year allowance for zero-emission vehicles, which had faded to 75% for 2024 and 2025 purchases, was reinstated at 100% for vehicles acquired on or after January 1, 2025 and available for use before 2030. It then steps down to 75% for 2030 and 2031 and 55% for 2032 and 2033. In plain terms, a Canadian business that buys a Tesla in 2026 and uses it for work can deduct the full capital cost, up to the $61,000 cap, in the first tax year, prorated for business use. The Canada Revenue Agency’s classes of depreciable property page has the current wording.
| Canadian Tesla (2026 pricing) | Capital cost before tax (incl. $2,500 freight/PDI) | Class 54 deductible amount | EVAP eligible? |
|---|---|---|---|
| Model 3 RWD, $39,490 | $41,990 | $41,990 plus non-recoverable tax, 100% in year one | No (Shanghai-built, not from a free-trade partner) |
| Model Y RWD, $49,990 | $52,490 | $52,490 plus non-recoverable tax, 100% in year one | Yes, $5,000, if you skip the $1,300 tow package |
| Model Y Premium AWD, $64,990 | $67,490 | Capped at $61,000 plus non-recoverable tax | No, over the $50,000 transaction cap |
| Model Y Performance, $74,990 | $77,490 | Capped at $61,000 plus non-recoverable tax | No |
A few Canadian wrinkles. The Cybertruck and Model X are not sold new in Canada in 2026, and there is no weight test anyway; a used Model X would be a Class 54 passenger vehicle under the same $61,000 cap. If a corporation owns the car and you also drive it personally, the standby charge and operating benefit (34 cents per kilometre in 2026) land on your T4, which is why many owner-managers hold the car personally and bill the company a tax-free allowance of 73 cents per kilometre for the first 5,000 km and 67 cents after that. Leasing is capped at $1,100 a month before tax and loan interest at $350 a month. Details on trims and delivery timing are in our Model Y Canada guide.
EVAP rebate or Class 54 write-off: Canadian businesses must choose
Businesses and organizations can claim up to 10 EVAP incentives over the life of the program, which runs from February 16, 2026 to March 31, 2031 or until the money runs out. As of September 2026 Transport Canada reported roughly $2 billion still available, but the incentive is first come, first served and scheduled to shrink over time, so check the EVAP program page before you order. The rebate is applied by Tesla at the point of sale; there is nothing to file.
Here is the decision most Canadian owner-managers get wrong. Since the original iZEV program launched in 2019, Ottawa’s rule has been one or the other: a vehicle that received the federal purchase incentive could not be placed in Class 54 for the enhanced write-off, and had to be depreciated as an ordinary Class 10.1 passenger vehicle instead. EVAP was designed as iZEV’s successor, and you should plan on the same either/or treatment applying, confirming the current wording with your accountant before you accept the rebate at delivery. Which choice wins depends on your tax rate and how much of the driving is business.
- Sole proprietor or professional in a high bracket, mostly business driving: Class 54 usually wins. On a Model Y RWD, deducting about $52,500 in year one saves a 45% taxpayer roughly $23,600 of tax now, versus a $5,000 rebate plus a slower Class 10.1 deduction that tops out at $39,000 in total.
- Small corporation paying the roughly 12% combined small-business rate: the rebate often wins. Five thousand dollars of cash today beats the tax value of an extra $13,500 of deductions at 12%, and the timing advantage of Class 54 is worth less at a low rate.
- Business use below about 60%: lean toward the rebate. Class 54 deductions are prorated by business kilometres; the rebate is not.
Quebec buyers can stack the province’s $2,000 Roulez vert credit on a Model Y RWD in 2026 regardless of which federal route they take, as long as the car is registered by December 31. And one more deductible line item for rural operators: if your crews work beyond cell coverage, a satellite internet kit for the truck or the site office is an ordinary business expense too; Canadian readers can order Starlink through our Starlink referral link, which is for Canada only and does not work for US addresses.
Timing: why “placed in service” beats “ordered” in both countries
Neither the IRS nor the CRA cares when you clicked Order. In the US the vehicle must be placed in service, meaning delivered and available for business use, by December 31. In Canada, Class 54 requires the vehicle to be acquired and available for use in the year, and EVAP is triggered by the transaction date at delivery. That matters in 2026 because Canadian Model Y orders placed in late summer were quoting delivery into December and January, and US Cybertruck inventory tightens every December as business buyers chase the same deadline. If a 2026 deduction is part of the plan, order early or shop existing inventory, which Tesla often delivers within two weeks. New orders for the Model 3, Model Y and Cybertruck placed through a Tesla referral link still receive three months of free FSD (Supervised) in both countries.
If you are not sure the vehicle will clear the 50% business-use test, or expect much higher income next year, leasing is worth a look; payments are deductible in proportion to business use with no depreciation election to unwind, and our lease vs. buy comparison has the 2026 numbers. US readers can check what incentives remain in our EV tax credit status guide, and the Canada Tesla and US Tesla sections collect our regional buying guides.
Frequently Asked Questions
Can I write off 100% of a Tesla Cybertruck for my business in 2026?
Yes, if it is used more than 50% for business and placed in service in 2026. The Cybertruck’s GVWR is well above 6,000 lb, so it is not subject to the passenger-automobile caps. You can combine Section 179 (up to $32,000 if it is treated as an SUV, or the full price if it qualifies as a six-foot-bed pickup) with 100% bonus depreciation on the remainder, and deduct the entire business-use portion of the cost in one year.
Does the Tesla Model Y qualify for Section 179?
It qualifies, but with a cap. Every Model Y trim has a GVWR under 6,000 lb, so it is a passenger automobile under Section 280F. For a vehicle placed in service in 2026 the first-year deduction is limited to $20,300 with bonus depreciation, then $19,800, $11,900 and $7,160 in later years, multiplied by your business-use percentage. Because a Model Y costs less than a typical luxury SUV, most trims are fully depreciated within three years anyway.
Is a used Tesla Model X still eligible for the heavy-SUV deduction?
Yes. Section 179 and bonus depreciation both apply to used property that is new to you and bought from an unrelated party. The condition is that the GVWR on the driver’s door certification label exceeds 6,000 lb. Most Model X builds do, some by a wide margin, but a few five-seat configurations sit only about 20 lb over the line, so read the label on the specific car before you buy.
How much of a Tesla can a Canadian business write off in 2026?
Up to $61,000 plus non-recoverable sales tax, and because the enhanced first-year allowance for zero-emission vehicles is back at 100% for vehicles acquired from 2025 through 2029, that entire amount can be deducted in the first year, prorated for business use. A Model 3 RWD or Model Y RWD falls fully under the cap; a Model Y Premium AWD or Performance is capped at $61,000.
Can a Canadian business get the $5,000 EVAP rebate and the Class 54 write-off on the same Tesla?
Plan on no. Under the predecessor iZEV program, a vehicle that received the federal incentive was excluded from Class 54 and had to use the ordinary Class 10.1 rules with a $39,000 cap. EVAP is built on the same framework, so treat it as an either/or decision and confirm the current rule with your accountant before accepting the rebate at delivery. High-bracket sole proprietors usually do better with Class 54; small corporations taxed at about 12% often do better taking the cash.
Did the $7,500 US EV tax credit come back in 2026?
No. Both the consumer clean vehicle credit and the Section 45W commercial credit ended for vehicles acquired after September 30, 2025, and no legislation to restore them has advanced. Depreciation is now the main federal tax benefit for a business buying a Tesla.
Key Takeaways
- In the US, the Cybertruck is the only new Tesla over 6,000 lb GVWR, so it can be written off in full in 2026 by stacking Section 179 (SUV cap $32,000) with permanent 100% bonus depreciation; a used Model X does the same if its door label reads over 6,000 lb.
- Model 3 and Model Y are passenger automobiles capped at $20,300 in year one, then $19,800, $11,900 and $7,160, but most trims are fully depreciated within three years.
- Business use must exceed 50%, a mileage log is mandatory, and claiming depreciation locks you out of the standard mileage rate for that vehicle; check your state’s conformity.
- In Canada, Class 54 lets a business deduct 100% of up to $61,000 plus non-recoverable tax in the first year for a Tesla acquired in 2026, with no weight test.
- Canadian businesses should expect to choose between the $5,000 EVAP rebate and the Class 54 write-off; high-bracket proprietors usually favour the write-off, low-rate small corporations the rebate.
- Deductions follow delivery, not the order date, so order early enough to take delivery before December 31.
Tax figures verified September 2026 against IRS Revenue Procedures 2025-32 and 2026-15, the Department of Finance Canada 2026 automobile limits release, CRA and Transport Canada program pages; prices are Tesla’s posted US and Canadian pricing at the time of writing and change without notice. This article is general information for US and Canadian readers and is not tax, legal or investment advice; rules vary by state and province and by your business structure, so confirm your plan with a licensed CPA or CPA (Canada) before acting. This article contains referral and affiliate links; see our disclosure page. Image credit: “2024 Tesla Cybertruck Foundation Series, front left (Greenwich)” by Mr.choppers, CC BY-SA 3.0, via Wikimedia Commons.

About the author: Lifei Zhou
Lifei is a Tesla owner based in Canada, writing practical, fact-checked Tesla guides for US and Canadian drivers — buying, ownership, insurance, charging, and TSLA investing, all from first-hand experience.